SIRC 2026: Buyer’s market that still demands discipline, Marsh Risk’s Jeremy Waite says
November 3 2026 by Andrew Mullen
Pricing is softening, but the risk landscape in Asia Pacific is becoming more complex, meaning a buyer’s market that still demands discipline, Jeremy Waite, head of APAC structured solutions at Marsh Risk, said.
“The balance between supply and demand is shifting. Traditional reinsurers, alternative capital and ILS investors are all still backing capacity across property and specialty lines,” he said.
“Pricing is softening, but retentions are staying fairly high, with reinsurers still cautious about moving attachment points down. So cedents are turning to aggregate covers, volatility solutions and other structured programs instead, to smooth out earnings without giving up capital efficiency.
“Wordings are getting sharper, too. Cyber, digital infrastructure, secondary perils and geopolitical risk all mean closer attention to definitions, aggregation and claims triggers. And parametric solutions are gaining traction wherever conventional occurrence-based cover doesn’t quite fit.”
The current risk landscape in the region is a “mixed picture”, according to Waite, with new exposures emerging fast even as recent losses have been fairly benign.
“Lower catastrophe activity has pushed capacity up and rates down. But don’t mistake that for things getting simpler. Near-term perils and exposure aggregation are both on the rise,” he added.
“Non-peak perils like flood, bushfire and severe convective storm matter more than ever. Cyber is accelerating too, with AI shrinking the gap between a vulnerability being found and being exploited, so losses can hit faster and cluster across companies sharing the same software, cloud or digital infrastructure.”
Data centres, Waite added, also stand out.
“We’re talking campuses with insured values north of US$10 billion, which means serious accumulation across property, construction, cyber and operational risk,” he said.
“Managing that properly takes better data, stronger aggregation tools and capital structures built for complex, multi-class risk.”
The appetite for Asian risk is still healthy, “just more selective”, Waite said.
“Reinsurers want to see good data quality, a balanced portfolio, solid loss experience and a clear underwriting strategy,” he added.
“Softening in the primary market is squeezing rate adequacy, especially on proportional treaties.”
APAC rates have now fallen for 11 quarters in a row, down by about 12% in the Pacific and 6% in Asia in Q3 2026, according to Waite.
“So, disciplined risk selection really matters,” he added.
“Capacity is still there for well-managed, diversified portfolios with transparent exposure data. Digital infrastructure, cyber and parametric cover remain good growth areas, as long as the structures reflect the real risk, not just the market.”
Hard market?
Digital infrastructure and cyber, as well as construction and specialty, will be key focus areas for Marsh Risk over the next 12 months, backed by advanced analytics and AI-enabled tools that turn complex model output into clearer decisions, according to Waite.
“We’re targeting growth right across APAC while building out solutions for emerging risks. In established markets, we’re going deeper on structured reinsurance like aggregate protection and volatility management, and connecting clients to both traditional and alternative capital,” he said.
“Casualty matters too, particularly legacy transactions, adverse development covers and loss portfolio transfers that help cedents deal with prior-year exposures.”
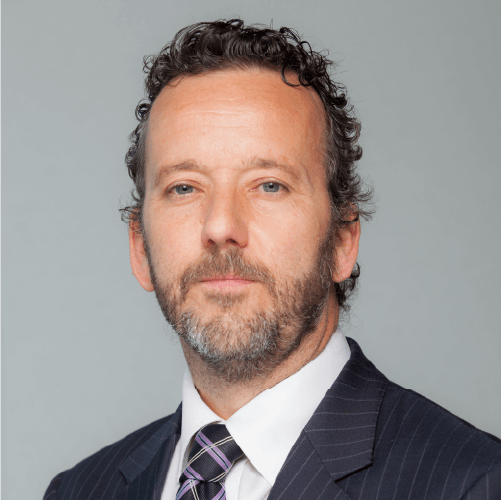
“The big challenge is a mismatch – plenty of reinsurance capital chasing slower premium growth, made harder by data gaps, accumulation risk and geopolitical uncertainty. That said, the competition is presenting opportunities too.”
Jeremy Waite, Marsh Risk
Waite said that the cedents that get their data, structure and partnerships right today will be best placed when the market hardens.
“The big challenge is a mismatch – plenty of reinsurance capital chasing slower premium growth, made harder by data gaps, accumulation risk and geopolitical uncertainty. That said, the competition is presenting opportunities too,” he said.
“Get serious about granular data and analytics. Put the savings from core protection back to work, for example, structured volatility covers, parametric solutions and diversified capital partnerships.
“Stick with long-term partners who really understand your portfolio through the cycle.
“Sort out legacy exposures now, because the market will harden eventually.”
-
BlackRock | Rethink the rules: how TAA and ETFs are reshaping portfolio construction
BlackRock's Daniel Caderas and MSCI's Raman Aylur Subramanian explain why tactical asset allocation (TAA) and exchange-traded funds (ETF) have become essential as global markets fragment and static allocations lose their reliability.
-
BlackRock | Infrastructure comes of age for insurers
Are insurers capturing full value from the asset class? BlackRock shares its perspective.
-
Beazley | Navigating geopolitical risks at sea
Maritime shipping faces growing geopolitical threats — missiles, drones, GPS interference, and cyber sabotage — requiring better intelligence, crew welfare, and resilience measures.
-
Zurich | Why resilience will define the winners of Asia’s clean energy transition
Planning for future conditions from the outset can improve operational reliability, reduce potential disruption and protect long-term asset value.