SIRC 2026: Softening rates, Hong Kong’s ILS ambitions, India’s opening market to dominate in Singapore
November 2 2026 by Marcus Alcock
The extent of softening, Hong Kong’s ambitions as an alternative risk transfer hub and India’s expanding reinsurance market will be among the major talking points as the industry gathers in Singapore this week.
This year’s Singapore International Reinsurance Conference (SIRC) is very much one for the market makers, with just the right conditions for the astute broker to feast upon: increasingly competitive market conditions, abundant capacity and growing demand for innovative risk transfer solutions across Asia.
Here are the areas that I think are likely to dominate discussions in Singapore this year.
1. Pricing, attachment points
First and foremost, the direction of travel at forthcoming renewals will inevitably dominate discussions. Given that traditional capital has been replenished and alternative capacity continues to expand, cedents will be no doubt not only be seeking further improvements in pricing, but also in broader reinsurance structures.
Expect multi-year deals, structured solutions, facilities and all that one would expect in a truly soft market to gather momentum at this year’s conference as the APAC market confirms and underlines the direction of travel that we saw in Monte Carlo in September.
For reinsurers, the challenge will be that cliché of “maintaining underwriting discipline” amid intensifying competition, particularly in property catastrophe business.
I suspect that, despite the rhetoric, a fair bit of ground will be given here over the coming months, and the extent to which reinsurers are prepared to relax attachment points, broaden coverage or accept lower margins will be closely watched.
2. Managing nat cat risk
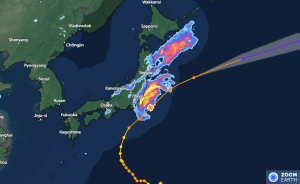 This has been a particularly benign year in terms of natural catastrophe losses, and the lack of a major land-forming hurricane to hit the US this year is significant (though of course the season could still have a sting its tail).
That said, natural catastrophe exposures will remain firmly on the agenda at SIRC, particularly given Asia’s vulnerability to typhoons, flooding and other severe weather events. This year I think the conversation will be particularly interesting, especially given the growing take-up of more innovative solutions in the reinsurance space of late.
As such, expect discussions to focus on the potential for parametric insurance, public-private partnerships and alternative capital to improve resilience in markets where insurance penetration remains low.
The growing significance of secondary perils and attritional catastrophe losses is also likely to feature prominently, alongside continuing concerns over whether existing models adequately capture changing exposures.
3. Merger fervour
The P&C (re)insurance market has experienced a wave of M&A activity this year, spread across the sector, involving specialty insurers, Lloyd’s syndicates and Japanese insurance groups. To date, we’ve had Zurich’s US$10.9billion takeover of Beazley, Sompo’s US$3.5 billion move for Aspen, AIG’s investment in Convex, and Starr’s acquisition of IQUW.
With no signs of the soft market changing direction any time soon, and impatient investors keen to make some decent returns, expect more of the same… with APAC very much in the limelight!
4. Indian market maturity
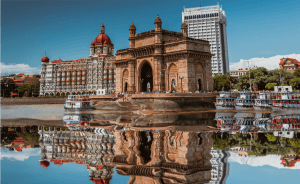 It has been a long time coming, but the once relatively closed-off Indian market is finally opening up to international investment on the reinsurance side. The development of Gujarat International Finance Tec-City (Gift City) is attracting growing international interest, as regulatory and tax incentives attract international reinsurers seeking access to India’s domestic market and opportunities elsewhere in Asia.
Indeed, reinsurance premium written through Gift City’s international financial services centre has increased more than fourfold to approximately US$608 million in the 2025–26 financial year.
Expect chatter at SIRC about how far demand for reinsurance is expected to increase across property catastrophe, agriculture, infrastructure, health and specialty lines as India’s economy develops and insurance coverage expands. However, questions still remain about pricing adequacy and the adequacy of catastrophe modelling.
Hong Kong’s ambitions
Hong Kong’s desire to establish itself as a leading regional reinsurance and alternative risk transfer hub are also likely to be a key talking point at SIRC.
In September, the territory’s government unveiled proposals to introduce protected cell company structures, designed to reduce the costs of establishing captive insurers and issuing insurance-linked securities (ILS).
The government also plans to review restrictions on ILS investors and expand catastrophe risk transfer capacity. Singaporean authorities will no doubt be watching with interest how this all plays out!
-
‘Huge opportunity, if we get it right’: brokers told to look beyond traditional insurance as risk pressures mount
- October 30
Worldwide Broker Network survey shows insurance has shifted from a transactional purchase to a strategic driver of resilience, but the landscape is complex and fast moving, global director of property and casualty and product development Jen Blair tells InsuranceAsia News.
-
‘You can’t fix what you can’t see’: cyber insurers warn PHP2Shell website shutdowns highlight AI impact
- October 27
Cyber insurers warn that the PHP2Shell shutdowns exposed a growing visibility gap as AI is now finding software flaws faster than clients can locate the systems running them.
-
Alternative solutions go mainstream as energy transition reshapes insurance risk
- October 26
Parametric design, basis risk, uninsured supply chains and the limits of catastrophe models were at the heart of the agenda at InsuranceAsia News' 2026 APAC Climate Risk & Insurance Summit in Singapore.
-
Changing economics of insurance call for transparency, long-term view: Prudential’s Douglas Flint
- October 23
Insurers must evolve from sellers of products into long-term 'life partners' for ageing populations, a shift that will require regulators, governments and educators to work together, says the insurer's chairman.
-
BlackRock | Rethink the rules: how TAA and ETFs are reshaping portfolio construction
BlackRock's Daniel Caderas and MSCI's Raman Aylur Subramanian explain why tactical asset allocation (TAA) and exchange-traded funds (ETF) have become essential as global markets fragment and static allocations lose their reliability.
-
BlackRock | Infrastructure comes of age for insurers
Are insurers capturing full value from the asset class? BlackRock shares its perspective.
-
Beazley | Navigating geopolitical risks at sea
Maritime shipping faces growing geopolitical threats — missiles, drones, GPS interference, and cyber sabotage — requiring better intelligence, crew welfare, and resilience measures.
-
Zurich | Why resilience will define the winners of Asia’s clean energy transition
Planning for future conditions from the outset can improve operational reliability, reduce potential disruption and protect long-term asset value.