

There’s no question that in a tough global environment, Asia Pacific remains a region of growth and opportunity. The kind of slowdowns anticipated in Europe and the US look less likely here. Perhaps as a result, there’s also a sense that inflation will remain relatively contained thanks to factors like the region’s more restrained stimulus in response to Covid-19, generally less tight labour markets and key position in global supply chains.
But Asia is not immune to economic challenges and there is a strong argument for more caution around the inflation outlook. Only a clear-eyed and realistic assessment of its impacts will ensure we can continue to mitigate risk and address the region’s protection gap challenges, while safeguarding a sustainable (re)insurance industry.
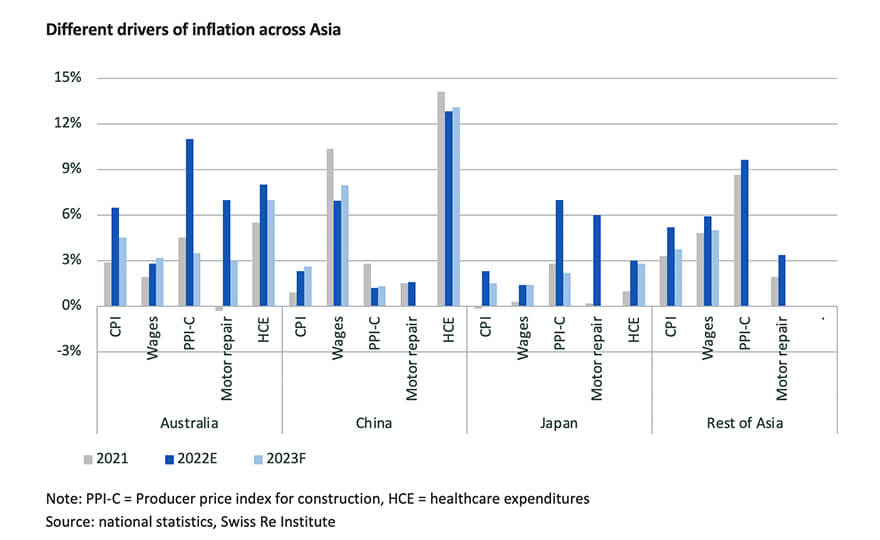
We see headline rates of inflation remaining relatively lower in APAC compared to other advanced markets, but rising costs are here to stay. Following the US Federal Reserve, some markets like New Zealand and Korea have just experienced the fastest interest rate hikes in more than a decade in their effort to fight inflation and rein in the interest rate differential with the US. Some underlying drivers of inflation, however, are more structural and harder to abate in nature; and policymakers must also take into consideration imported inflation and the lagged impact of a strong US dollar.
There are troubling spikes in some individual components of inflation emerging across the region. In Australia, for example, construction costs continue to rise at record rates, which will have a direct impact on the construction sector.
(Re)insurers should brace for impact
We need to be cognisant of, and prepare for, the knock-on effects on the (re)insurance sector. If we don’t take swift action to reprice for inflation, we’ll struggle to catch up, and to manage risks and provide coverage for businesses and consumers over the long term.
We are seeing demand surge turbo charge claims inflation. This is particularly prevalent as catastrophe events across the region continue to rise, increasing the cost of repair or replacement of damaged property, when many individuals and organisations vie for a limited supply of labour and materials.
As an industry, we must enter a period of adjustment across the entire value chain to ensure we fully account for volatility, and don’t simply absorb higher risks that could haunt us later.
When it comes to the impact of inflation. this applies across all structures. For non-proportional contracts, inflation increases the indexed value of historical losses. When retention is held constant, this increases the frequency and size of losses that are ceded into reinsurance treaties, and hence impact non-proportional treaty pricing. For proportional contracts, fixed-commission treaties become less economical if insurers are not able to adequately adjust the primary rate for claims cost inflation.
The confluence of increasing claims inflation and material mismatch in the demand-supply of reinsurance capacity means that reinsurance pricing needs to rise to reflect this. This particularly applies in an inflationary environment with a higher probability of market or disaster-driven shocks. Historical loss models should be updated to consider both changing assumptions about primary and secondary perils and the impact on insurance claims. Excess of loss costing will change, and margins will need to improve to reflect additional downside risk or volatility – and so the capacity to pay claims is maintained.
Retaining capacity
This recalibration will be a delicate, at times difficult, process. But given the current situation, the pain of inaction could be even greater. (Re)insurers must also remain financially sound to ensure the capital that underpins our ability to help our clients manage risks remains sustainable.
Instead of indifference, or inaction, I call on the industry to confront inflation and the new risks that arise in its wake with level-headed evaluation. APAC is not alone in this struggle: whether the effects of climate change, the Ukraine conflict or supply chain disruption, the challenges exacerbating risks and costs are global. Similarly, reinsurance capital is a global commodity, and we should view our efforts as part of a concerted global response.
Amid this volatility, insurers should be thinking about how they are going to compensate themselves for the risks they take. In our discussions, our message to insurers is primary pricing must respond; anticipate change in reinsurance programmes by increasing retentions and engaging early to avoid missing out or paying a heavy price.
This article was written by Mark Senkevics, Swiss Re’s Head of Property & Casualty Underwriting for Asia, Australia & New Zealand.
-
Fire losses: Penang Bridge ruling shows why the first days on site matter most
- October 19
In February 2021, fire damaged the Penang Bridge, one of Malaysia’s most important pieces of public infrastructure. More than five years later, the High Court of Malaya has ruled on its cause, ordering Tenaga Nasional to pay RM10.5 million (US$2.6 million) to Projek Lebuhraya Usahasama. The court heard two explanations. One was that an external […]
-
Claims: Same asset, different market: why regulatory fragmentation changes how insurance responds in Asia
- October 5
Asia’s insurance market comprises many countries, each operating under its own rules, practices and market norms. These differences influence not only how insurance is placed, but also how it performs when tested by a loss. Commentary on Asia’s compelling growth story can sometimes overlook the complexity and distinctiveness of the individual markets that make up […]
-
Infrastructure: Data centres are racing ahead of the rules built to insure them
- September 21
Data centres have become a defining infrastructure story of the AI era, particularly in the Asia Pacific region. A single hyperscale facility can now draw more than 100MW, and in Malaysia alone roughly 13GW of data centre capacity is either planned or already under development. Behind every one of those numbers sits a construction and […]
-
Risk management: Insurance lessons from one of China’s deadliest industrial accidents in recent years
- July 20
The explosion at a Chinese fireworks factory at the start of May is a reminder that the true value of an insurance program is tested not when a policy is purchased, but when catastrophe strikes. The fire at the Huasheng Fireworks Manufacturing and Display Company in Liuyang, Hunan province, claimed 37 lives, injured 51 people, […]
-
Beazley | Navigating geopolitical risks at sea
Maritime shipping faces growing geopolitical threats—missiles, drones, GPS interference, and cyber sabotage—requiring better intelligence, crew welfare, and resilience measures.
-
Zurich | Why resilience will define the winners of Asia’s clean energy transition
Planning for future conditions from the outset can improve operational reliability, reduce potential disruption and protect long-term asset value.
-
Sedgwick | Captives in Asia: From Niche Solution to Strategic Risk Platform
Captive insurance has evolved from niche tool to strategic risk infrastructure in Asia, with connected claims data seen as key to unlocking its full value.
-
BlackRock | Rethink the rules: how TAA and ETFs are reshaping portfolio construction
BlackRock's Daniel Caderas and MSCI's Raman Aylur Subramanian explain why tactical asset allocation (TAA) and exchange-traded funds (ETF) have become essential as global markets fragment and static allocations lose their reliability.
Mark Senkevics, Swiss Re
Confronting inflation to avoid playing catch up at renewals
Mark Senkevics, Swiss Re