Get full access
To view the full article and get unlimited access to InsuranceAsia News's exclusive insight across 5,000+ articles
Already a Subscriber? Please Login

Asia’s reinsurance market continues to be competitive and it is a “challenging renewal season”, but what is important is to continue to focus on understanding the risk and portfolio quality, according to Anna Ziswiler, managing director and head of P&C reinsurance Asia (ex-China, ex-Japan), at Swiss Re.
“Asia is very diversified. It does vary across the different markets, across the different lines of business, and also varying across client portfolios,” she said.
As the market is becoming more competitive, the underlying risk and risk environment is certainly not getting less complex, she added, meaning understanding the risk is key.
“Certainly, looking back as well at historical performance, but also really understanding the trends that are shaping the risk of tomorrow, making sure that structures, coverages are really well understood and that they’re really commensurate with the risk that we’re taking,” Ziswiler said.
Portfolio quality is the most important thing to look at in this environment, she added.
“We will of course look at competitive pricing, but what is the quality of that portfolio, how are our clients thinking about accumulation and concentration,” she said.
Despite the pricing pressure, Ziswiler said Asia’s structural growth story is intact.
Urbanisation, infrastructure spending, manufacturing investment and rising insurable values continue to create demand for protection.
“There should also be a very inherent opportunity that you see in Asia just as at the back of economic development, the urbanisation, and the infrastructure investments, manufacturing investments that you see in the region,” she said.
“Our approach is we will and can grow where the economics are going to make sense, where the economics also justify the risk that we’re undertaking for us to really be the sustainable partner to our clients.
“Growth for Swiss Re in Asia will primarily come from two distinct areas to start with. One is natural catastrophes…the second one I would say is the infrastructure investments that we’re just seeing across that drives needs of insurance when it comes to engineering, some of our specialty solutions.”
She added that clients are increasingly asking how reinsurance can support expansion.
“Clients are wondering if reinsurance is an option for them and how can Swiss Re help fund that growth—equity versus debt,” Ziswiler said.
Ziswiler said data centre exposure spans nearly every line of business.
“You really go across all the lines of business. Cargo, engineering, property, business interruption, liability, cyber, it’s really the whole suite,” she said.
The risks are well understood, from design to construction to commissioning and to production, she added.
The challenge is not only pricing individual risks, but understanding how they connect.
“I think where we need to spend more time and attention on is how are all those risks interconnected and how are they concentrated?” she said. “What I think is the most important is the data quality, the transparency, how are we looking at this accumulation and the concentration, how it’s built, how do those policies interact.”
Ziswiler described current client discussions as constructive, even in a market where buyers have more leverage.
“Generally, the conversations are very open, very productive and constructive in terms of what the situation is at the moment and where our clients can find solutions for some of those needs,” she said.
Swiss Re intends to remain a consistent partner to strategic clients through market cycles, but performance will matter.
“We will be deploying capacity where the rate adequacy also fits the risk view that we have,” Ziswiler said.
Beyond property cat, Swiss Re sees momentum in specialty classes—particularly marine, engineering and agriculture.
“Within specialty lines, you really have some micro-cycles within a cycle,” she said. “And then, specialty is also very much driven by the loss experience, like any lines of business. My experience in some of the very specialised lines where you also have huge demands, very complex risk, you sometimes have a different balance of supply and demand.”
Facultative reinsurance is another area where demand is rising.
“Across Asia, we’ve also seen an uptick when it comes to facultative demand,” she added.
Markel plans to double down on specialty growth in Southeast Asia following the recent unification of its Singaporean and Malaysian units, according to its regional chief.
Kevin Leung, who was recently appointed managing director for Southeast Asia, said that the Lloyd’s specialty carrier is targeting expansion of its specialty business in the region, particularly its marine and financial lines offerings.
“The idea really was to create a seamless platform for us to more effectively address all our clients’ needs and to tackle the regional opportunities while also creating a more interesting platform for people to work on where they could develop their skills in a regional setting,” said Leung.
According to Leung, the unification is partly also a reflection of Malaysia’s growing importance and potential as a market for specialty insurance.
In recent years, Malaysia has emerged as one of the fastest-growing economies in the region thanks to its status as a hub for electronics manufacturing and data centres amid the ongoing global AI boom.
“One of the main pillars of growth over the past two years has been in the construction industry where there’s been a lot of investments going into AI data centres and related areas,” Leung said.
“I see a lot of potential opportunities from a specialty perspective. The obvious one is construction. But then if you look at all the other things that we do, marine cargo, project cargo, cyber, commercial general liability and such, I think there are more things that would benefit from the growth in this particular segment.”
Leung also cited Malaysia’s cyber market as an area where specialty insurers have significant headroom to grow.
“With all these new developments, renewables, data centres, and also infrastructure investments and just the general wealth and population growth, there will be a lot of specialty opportunities that come with all that,” he added.
The marine market remains at the core of Markel’s long-term ambitions in the region, despite the significant disruptions suffered this year due to the conflict in the Middle East.
Heading into 1.1 renewals, the marine market is unlikely to see any improvement, given the lack of regional stability, with the current softening rates rapidly becoming “unsustainable”.
“I think the market will get to a point where we will have to see some hardening, because the current rate of reduction is simply not sustainable,” Leung said. “And all the premiums coming from the war side of things, that’s not your sort of regular marine income stream. That’s really born out of exceptional circumstances. Once that fades away, it is the core hull and cargo business that will need to sustain the marine insurance market.
“Unfortunately, we are not seeing the right signs at the moment for 2027. So I would still expect the market to become more competitive. This trend, I think, has to reverse, hopefully sooner rather than later because at some point more and more players will suffer losses and that is simply not sustainable in the long run.”
“Ultimately, I think our aspiration is really to be an outsized contributor to the bottom line of Markel as we’ve done in the past two years now.” Kevin Leung, Markel
According to Leung, the softening in the marine market is likely to stabilise in the medium term from the 10-15% rate of reductions seen during recent renewals. The specialty insurer also sees growth opportunities arising from the ongoing shipbuilding boom in India, China and South Korea.
“We are actually seeing some other opportunities that dovetail quite well with our regular marine hull portfolio, and I believe we are well positioned to take advantage of emerging opportunities as well,” Leung said. “I’m somewhat bullish in the M&E liabilities space especially vis-a-vis construction. We’ve got a new business that’s coming online and that’s part of our recent acquisition of MECO and that will offer us additional diversification into the P&I and charterers areas.
“Generally, the market will be a bit more sensible going into 2027 in the liability areas because of how uncertain the cost environment is. And the liability environment in the US and elsewhere is also getting a bit more unpredictable.”
Markel completed the acquisition of specialist marine managing general agent, The MECO Group, in June 2025, following regulatory approval.
Markel sees APAC as a critical component of its long-term growth plans and diversification, with the carrier targeting a 50:50 split between its London business and the rest of the world, with APAC accounting for 10% of its total international business by 2030, up from 6-7%.
“Ultimately, I think our aspiration is really to be an outsized contributor to the bottom line of Markel as we’ve done in the past two years now,” Leung added. “Our ambition is to grow our APAC business to US$500 million over the next three to five years, while staying on this sustainable and profitable growth path.”
I guess we’ve all been in situations where we feel we’re not properly qualified to be there and there’s surely been some mistake, but – as a journalist with 30 years of experience writing about the (re)insurance market – I never thought that this feeling would happen to me at an industry conference. Yet imposter syndrome crept upon me at the end of the address by Chee Hong Tat, Minister for National Development and deputy chairman of the Monetary Authority of Singapore.
There I was, perched on end of a front row seat which I had nabbed in order to take some decent photographs of the speakers and to make sure I could have a clear audible record of the addresses. Suddenly everyone in my row stood up and the minister came down and passed down the line, shaking everyone’s hand – clearly this was some sort of official delegation. When he came to me and offered his hand, I could hardly remain seated, so I stood up and shook his too. A proper imposter!
Next on stage was Thierry Léger, CEO of Scor. Often at these conferences these sorts of keynotes can be filled with platitudes, but here Léger offered words that left me with a really uneasy feeling as I wondered what the ultimate outcome of all of this will be.
One of his main topics, you won’t be surprised to learn, what that of AI, and the implications this will have for the wider (re)insurance market. Here Léger was clear that this technology will be transformative for the market, but will not be without its problems, most notably lingering issues over reliability and the need for proper oversight.
Yet his most telling revelation, as we wrote in yesterday’s edition, was that Scor has this year been piloting a fully autonomous AI underwriting system, with, in theory, no need for human involvement in the actual underwriting process. Yes, you heard that right: this system is able not only to analyse the risk, but also to assess the commercial rating environment and then to quote and bind. No flesh and bone involved.
Léger was fairly clear that human oversight and proper governance protocols will still be needed for such AI underwriting tools, but the brutal reality here is obvious: in future, there will be need for considerably fewer underwriters than there are at present if AI can automate the whole process. Sure, experienced market players will still be needed to check that these AI agents are going AWOL. But how many of these will really be needed? And what happens to the rest? I fear that we could be at the start of a wave of serious culling in the market. And not just for underwriters, right? AI is both amazing and terrifying in equal measure. Gulp.
The reinsurer’s role in Japan is being reshaped as clients increasingly seek expertise, data, modelling and international experience alongside balance-sheet capacity, a trend expected to accelerate, according to Munich Re Japan CEO Florian Gruson.
“Innovation in Japan may therefore lie less in standalone products than in bringing insurance, technology, prevention and capital solutions together,” Gruson said.
Japan’s investment cycle is broadening the country’s risk landscape as new factories, digital infrastructure and technology investments create insurable value, but also introduce concentrations and interdependencies that require careful assessment.
“Risk assessment must extend beyond physical asset values. Property, business interruption, cyber and liability exposures are increasingly interconnected. Power availability and infrastructure dependencies are also becoming more significant considerations, for example, data centre development,” he said.
The opportunity for the industry is to help make the investment-led growth resilient, as carriers must combine risk expertise, prevention and modelling with sustainable risk-transfer capacity.
The scale of semiconductor investments and data centre developments presents opportunities for the industry to support Japan’s economic development.
“This growth calls for sophisticated risk assessment and disciplined underwriting. Capacity, pricing and terms must reflect individual risk quality and the potential accumulation of exposures,” Gruson said.
Cyber is another prominent developing exposure for Japan, he added.
“Recent attacks underline that cyber is not simply a technology issue, but a systemic business risk with implications for operations, supply chains and customer trust,” Gruson said.
“Vulnerabilities at cloud providers, technology vendors and other third parties can transmit disruption across multiple organisations. This is also true for cars, which have evolved into connected, software-driven computers, with software-defined vehicles and autonomous vehicles being prominent examples.
“This creates liability risks for manufacturers and other service providers well beyond the day of sale.”
Sustainable cyber capacity requires disciplined underwriting, transparent risk information and close cooperation among clients, technology specialists, government, insurers and reinsurers.
According to Gruson, cyber is now Munich Re Japan’s second-largest P&C business line after property natural catastrophe.
The new exposures sit alongside Japan’s established nat cat risks.
While major typhoons and earthquakes remain central to risk management in Japan, the increasing frequency of localised weather-related losses is a growingly important consideration for the natural catastrophe market.
Heavy rainfall, flooding and hail have become significant sources of loss. Japan has seen weather records repeatedly rewritten in recent years, from unprecedented rainfall and heat to unusual typhoon tracks and landfalls.
“The aggregate impact of these secondary perils on an insurer’s portfolio can be substantial,” Gruson said. “High-quality data is essential to a robust assessment of these evolving exposures.”
Meanwhile, Japan’s P&C market is undergoing a structural transformation that extends beyond consolidation, as governance, distribution, capital management and underwriting discipline are evolving in parallel.
“Following the conduct and governance issues of recent years, restoring trust and strengthening oversight remain priorities,” Gruson said.
“Our Japan market assessment points to sustained regulatory and industry focus on agency oversight, sales practices and distribution reform. Implementation will take time, but these measures should strengthen the quality and professionalism of insurance provision across the market.”
Japanese insurers are also placing greater emphasis on technical profitability and reallocating capital towards overseas expansion, M&A and adjacent businesses.
“As their risk profiles evolve, reinsurers can play an increasingly important role in supporting these growth strategies,” he said.
Regulatory change is also shaping capital decisions after Japan’s new economic value-based solvency ratio framework took effect at the end of March.
The Financial Services Agency has indicated that it would continue assessing insurers’ financial positions and risk-management frameworks under the new regime.
“Taken together, these changes are laying the foundation for the industry’s next chapter,” Gruson said. “These developments reinforce the importance of a strategic dialogue with clients on how reinsurance can manage volatility, improve capital efficiency and enable sustainable growth.”
Peak Re will diversify its offering in India to provide more facultative and specialty lines cover, even as fresh capacity intensifies rate pressure across the market, according to Sudhir Salian, head of India and Middle East.
Salian said the global insurance rates are softening, and similar effects will be visible in India, particularly because of the price sensitivity of Indian cedents.
However, the Hong Kong reinsurer said it will maintain its underwriting discipline amid rising risk exposures.
“At the same time, the entry of additional onshore reinsurers has expanded local capacity and intensified competitive pressure. The impact on pricing is already evident in the rate adjustments seen in the direct property insurance segment. Barring a significant market-changing loss, we expect this trend to continue,” he added.
However, the combination of declining prices and growing exposures is prompting Peak Re to examine its portfolio more closely as the market approaches its next major renewal.
“Rising aggregate exposures, continued rate erosion and several losses in India during the year have heightened our focus on portfolio dynamics and management. We will therefore monitor market developments closely and assess their implications for the April 1 renewal,” Salian said.
Despite the competitive environment, Peak Re intends to maintain a selective underwriting approach, according to Salian.
“We will maintain a selective and disciplined approach, focusing on cedents whose underwriting practices we understand and trust. Our objective is to build long-term relationships that allow us to support clients as they strengthen and expand their business,” he said.
The company also plans to diversify its portfolio and expand its capabilities beyond traditional reinsurance business.
“In terms of portfolio management, Peak Re will continue to diversify its offering, globally as well as in India, partly by building on its recent success in structured solutions,” he added.
“Going forward we also expect to provide more facultative coverage and steadily grow our underwriting capabilities across specialty lines.
“At the same time, the adoption of IFRS 17 and risk-based capital frameworks will drive demand for structured and capital-management solutions.”
Indian insurers began transitioning to Indian Accounting Standards in April 2026, while the Insurance Regulatory and Development Authority of India (IRDAI) has been working towards implementing a risk-based capital framework from April 2027.
India’s reinsurance market has been attracting additional domestic and international capacity, and more than 20 reinsurers have established operations in the Gujarat International Finance Tec-City Special Economic Zone (Gift City), India’s special economic zone
“Gift City has grown rapidly. By the end of the first quarter of 2026, it had attracted 36 insurance entities, including 22 reinsurers, and premiums had reached approximately US$650 million in FY26. More capacity gives cedents more choice,” Salian said.
Operating in the Indian insurance market for more than a decade, Peak Re was among the first reinsurers to receive a licence at Gift City in early 2025, he added.
Effective this year, India’s insurance regulator, the the Risk-Based Capital and Risk-Based Solvency frameworks. Over time, these developments may influence direct insurers’ demand for reinsurance protection.
“Benefiting from our first-mover advantage in Gift City, we gained substantial traction since we received our branch licence and are now among the larger reinsurers operating in Gift City,” Salian said.
“We underwrite a broad spectrum of risks across multiple classes of business, including property, engineering, motor, health, credit and surety, agriculture, structured solutions and life insurance.”
According to Salian, the size and potential future growth of the market speaks volumes of imminent opportunities. India is currently the 10th largest insurance market with a premium volume of approximately US$151 billion, but its insurance penetration of 3.7% is still well below the global average of 7.3%.
However, the prospects are improving, considering India’s dynamic GDP growth, forecast at 6% for 2026, together with its significant protection gap.
Government initiatives such as “Insurance for All by 2047”, aims to broaden access to life, health and property insurance for consumers and businesses, according to Salian.
The Indian government has also allowed 100% foreign direct investment in insurance, attracting additional capacity to the country. International players’ interest is mirrored by that of domestic insurers, which are also accelerating their expansion, he explained.
“Thus, despite the softening of rates both globally and regionally, the Indian insurance market remains highly attractive,” Salian said.
Indian insurers are looking beyond price and capacity for partners that are able to support their growth through expertise sharing, a broad product offering and a commitment to advance the overall market, he added.
Pricing is softening, but the risk landscape in Asia Pacific is becoming more complex, meaning a buyer’s market that still demands discipline, Jeremy Waite, head of APAC structured solutions at Marsh Risk, said.
“The balance between supply and demand is shifting. Traditional reinsurers, alternative capital and ILS investors are all still backing capacity across property and specialty lines,” he said.
“Pricing is softening, but retentions are staying fairly high, with reinsurers still cautious about moving attachment points down. So cedents are turning to aggregate covers, volatility solutions and other structured programs instead, to smooth out earnings without giving up capital efficiency.
“Wordings are getting sharper, too. Cyber, digital infrastructure, secondary perils and geopolitical risk all mean closer attention to definitions, aggregation and claims triggers. And parametric solutions are gaining traction wherever conventional occurrence-based cover doesn’t quite fit.”
The current risk landscape in the region is a “mixed picture”, according to Waite, with new exposures emerging fast even as recent losses have been fairly benign.
“Lower catastrophe activity has pushed capacity up and rates down. But don’t mistake that for things getting simpler. Near-term perils and exposure aggregation are both on the rise,” he added.
“Non-peak perils like flood, bushfire and severe convective storm matter more than ever. Cyber is accelerating too, with AI shrinking the gap between a vulnerability being found and being exploited, so losses can hit faster and cluster across companies sharing the same software, cloud or digital infrastructure.”
Data centres, Waite added, also stand out.
“We’re talking campuses with insured values north of US$10 billion, which means serious accumulation across property, construction, cyber and operational risk,” he said.
“Managing that properly takes better data, stronger aggregation tools and capital structures built for complex, multi-class risk.”
The appetite for Asian risk is still healthy, “just more selective”, Waite said.
“Reinsurers want to see good data quality, a balanced portfolio, solid loss experience and a clear underwriting strategy,” he added.
“Softening in the primary market is squeezing rate adequacy, especially on proportional treaties.”
APAC rates have now fallen for 11 quarters in a row, down by about 12% in the Pacific and 6% in Asia in Q3 2026, according to Waite.
“So, disciplined risk selection really matters,” he added.
“Capacity is still there for well-managed, diversified portfolios with transparent exposure data. Digital infrastructure, cyber and parametric cover remain good growth areas, as long as the structures reflect the real risk, not just the market.”
Digital infrastructure and cyber, as well as construction and specialty, will be key focus areas for Marsh Risk over the next 12 months, backed by advanced analytics and AI-enabled tools that turn complex model output into clearer decisions, according to Waite.
“We’re targeting growth right across APAC while building out solutions for emerging risks. In established markets, we’re going deeper on structured reinsurance like aggregate protection and volatility management, and connecting clients to both traditional and alternative capital,” he said.
“Casualty matters too, particularly legacy transactions, adverse development covers and loss portfolio transfers that help cedents deal with prior-year exposures.”
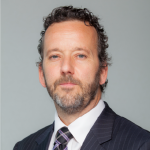
“The big challenge is a mismatch – plenty of reinsurance capital chasing slower premium growth, made harder by data gaps, accumulation risk and geopolitical uncertainty. That said, the competition is presenting opportunities too.”
Jeremy Waite, Marsh Risk
Waite said that the cedents that get their data, structure and partnerships right today will be best placed when the market hardens.
“The big challenge is a mismatch – plenty of reinsurance capital chasing slower premium growth, made harder by data gaps, accumulation risk and geopolitical uncertainty. That said, the competition is presenting opportunities too,” he said.
“Get serious about granular data and analytics. Put the savings from core protection back to work, for example, structured volatility covers, parametric solutions and diversified capital partnerships.
“Stick with long-term partners who really understand your portfolio through the cycle.
“Sort out legacy exposures now, because the market will harden eventually.”
Ahmad Noor Azhari, president and CEO of Malaysian Re
What are the major trends you are seeing in Malaysia, along with the wider Asian market, for the upcoming renewal, in terms of capacity, pricing, retention and wordings?
We expect the upcoming renewal season to remain favourable for buyers, supported by ample reinsurance capacity across Malaysia and Asia. Competitive market conditions are likely to keep pricing under pressure, although we do not expect the pace of softening to be as pronounced as previous renewals.
Retentions are expected to remain broadly stable, with some cedents using premium savings to enhance protection or optimise programme structures.
While wordings are generally expected to remain stable, there is growing interest in alternative solutions and more tailored reinsurance arrangements.
How do you view the current risk landscape?
Climate and natural catastrophe risks continue to be key concerns, while emerging risks such as cyber, healthcare inflation and longevity trends are reshaping the risk environment.
As risks become more complex, reinsurers are expected to provide not only capacity but also technical expertise, underwriting insights and risk management support.
In this environment, strong partnerships, knowledge sharing and long-term commitment are increasingly valued by cedents.
How is your appetite for risk evolving? Do you see softening in the primary market impacting rate adequacy as a concern, especially for your proportional treaties?
Our appetite remains growth-oriented but disciplined. We continue to support our clients while maintaining a strong focus on underwriting fundamentals, portfolio quality and sustainable profitability.
While softening primary market rates are closely monitored, our approach is centred on long-term partnerships rather than short-term market cycles.
We also continue to explore innovative and alternative structures where they can help clients achieve their objectives while maintaining appropriate risk parameters.
What are the business growth strategies and focus areas for Malaysian Re in the next 12 months, in terms of geography as well as lines of business?
Our strategy is focused on building a diversified and sustainable portfolio while continuing to support market resilience and insurance development in Malaysia.
Regionally, we aim to deepen relationships with selected clients across Asia and expand in areas where we have strong expertise. We also continue to expand our presence in other territories, supported by strong cedent relationships across the London Market, Europe, the Middle East, and selected markets worldwide.
Key focus areas include specialty lines such as energy, credit and surety, medical business, and structured solutions including parametric offerings. Across all markets, our priority is sustainable profitability, long-term partnerships and delivering value-added technical expertise.
What are the concerns and challenges you have in the Asian market?
One of the key challenges in Asia is balancing abundant market capacity with the need to maintain underwriting discipline and sustainable profitability. As risk landscapes evolve, it is increasingly important for reinsurers and cedents to work closely together, sharing insights, technical knowledge and strategic direction.
What is your advice for cedents?
Our advice to cedents is to focus on long-term partnerships, maintain open dialogue with reinsurers and remain receptive to innovative solutions that can strengthen resilience and support sustainable growth.
The upcoming 1.1 renewals are set to be characterised by discipline and differentiation rather than broad market movements, Mukul Kishore, CEO of Scor Reinsurance Asia Pacific and head of Asia Pacific P&C, said.
“The central question is no longer whether sufficient capacity exists. It is whether capital is being deployed in a way that supports both profitable growth and long-term resilience for the industry and its clients,” Kishore said.
“The key question for APAC is no longer whether capacity is available. It is how industry can deploy capital, expertise and technology to narrow protection gaps while preserving long-term insurability.”
Heading into 2027, Scor will stay focused on underwriting discipline, client partnership and regional resilience in the region, Kishore said, keeping strong standards and disciplined capital allocation to sustain profitability through every market cycle, deepening relationships with expertise and tailored solutions rather than purely transactional deals, and helping the industry adapt to evolving climate and emerging risks.
Amid the ongoing market softening, Kishore insists Scor’s approach remains consistent, with a focus on profitable and sustainable growth “rather than growth for its own sake”.
“Our risk appetite continues to be guided by technical fundamentals, portfolio balance and long-term value creation. We continuously assess opportunities across markets and segments, but our objective is not to chase market share. Instead, we remain disciplined in deploying capital where we believe risk-adjusted returns are attractive,” he said.
“In terms of growth opportunities, APAC continues to offer considerable potential. Protection gaps remain substantial across many emerging markets, particularly in Southeast Asia. We see opportunities in supporting economic growth through traditional property and casualty reinsurance, while also helping clients address emerging risks.
“Areas such as climate resilience, specialty lines, alternative risk transfer and parametric products are likely to play an increasingly important role. More broadly, we see significant opportunities in partnering with clients to improve risk understanding, enhance portfolio management and develop innovative solutions that address evolving customer needs.”
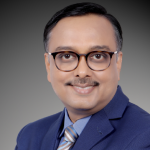
“While capacity remains available, I expect continued differentiation. Reinsurers will remain focused on risk-adjusted returns, and cedents that demonstrate strong underwriting performance, high-quality data and disciplined exposure management should continue to benefit from constructive reinsurance support.”
Mukul Kishore, Scor
Heading into the 1.1 renewals, the APAC reinsurance market remains fundamentally well supported, according to Kishore, with reinsurers entering the renewal season with healthy balance sheets and improved profitability following several years of underwriting discipline and portfolio optimisation.
“While capacity remains available, I expect continued differentiation. Reinsurers will remain focused on risk-adjusted returns, and cedents that demonstrate strong underwriting performance, high-quality data and disciplined exposure management should continue to benefit from constructive reinsurance support,” he said.
“From a pricing perspective, the broad-based hardening cycle is now largely behind us. We are seeing a more nuanced market, with outcomes increasingly driven by individual portfolio performance rather than overall market conditions.
“Where underlying risks have performed well and technical adequacy remains intact, pricing should remain relatively stable. At the same time, loss-affected portfolios or areas where exposure trends are not adequately reflected in pricing will continue to attract scrutiny.
“Retention levels are likely to remain broadly aligned with recent years, reflecting the industry’s greater focus on earnings volatility management and the need to preserve reinsurance capacity for more severe events.
“On wordings, I do not expect a significant reversal of the improvements achieved over the last few renewal cycles. Clarity, contract certainty and disciplined coverage management will remain important priorities for reinsurers.”
The industry must stay vigilant on rate adequacy as exposures, climate risks and loss trends evolve, Kishore said.
“The objective should not be to maximise short-term premium growth, but rather to ensure that pricing appropriately reflects the underlying risk,” he said.
While targeted adjustments may occur where portfolios perform well, reinsurers will likely preserve contract clarity, attachment points and sustainable risk-adjusted returns, Kishore added.
This year, according to Kishore, showed nat-cat risk remains significant and evolving.
“The frequency and severity of weather-related events reinforce the importance of risk selection, portfolio diversification and technical pricing discipline,” he said.
Growing exposure concentrations across Asia Pacific, driven by urbanisation and infrastructure growth, plus rising secondary perils like floods, underscore the need for better risk modelling, data quality and resilience measures, Kishore added.
Rate adequacy for financial lines, including cyber, remains an active discussion across the industry, particularly after several years of pricing pressure in certain segments, according to Emily Poh, head of APAC financial lines at Sompo in Singapore.
“Market competition remains strong across most financial lines products,” Poh said. “Capacity is broadly available, and claims activity has been relatively stable in several areas, with cyber being a more nuanced exception.
“This continues to create pricing pressure, particularly for well-managed risks with strong loss performance.”
However, the risk environment is becoming more complex, and directors and officers are operating under greater scrutiny from regulators, shareholders and other stakeholders.
Corporates are also managing geopolitical uncertainty, economic volatility, technological change and a fast-evolving cyber threat landscape.
“In D&O, the concern is less about the current claims environment and more about the potential severity of future losses,” Poh added. “Regulatory investigations, securities litigation, governance failures and emerging risks can take years to emerge and develop. It is important that pricing continues to reflect the long-tail nature of the product.”
In cyber, the discussion is more immediate with the ongoing global AI and data centre boom transforming the threat landscape, according to Poh.
“The threat environment continues to evolve rapidly, and organisations have never been more reliant on technology, data, cloud infrastructure and digital supply chains,” Poh said. “Maintaining the right balance between market competitiveness and long-term sustainability is critical.”
Concentration risk in cyber is an area that needs closer scrutiny as businesses become more dependent on major technology providers, cloud platforms and interconnected supply chains, meaning a single event can have implications across multiple sectors and geographies.
“Businesses are increasingly dependent on interconnected technology ecosystems, cloud platforms, managed service providers and third-party vendors,” Poh added. “That creates the potential for broader and more systemic impacts from a single cyber event.”
In the cyber insurance market, there is a growing mismatch between the soft rate environment and the increasingly complex threat landscape, which shows little sign of abating in the short term, according to Poh.
“There is certainly a tension between the pricing environment and an increasingly complex cyber risk landscape,” she said.
“The growth of artificial intelligence adds another layer of complexity. AI can help improve security, efficiency and detection capabilities, but it may also increase the speed, scale and sophistication of cyber threats.”
The cyber insurance market has shown resilience in recent years, supported by improved underwriting standards, stronger risk selection and greater focus on cyber maturity.
Cyber insurance in APAC has potential for growth given the region’s large cyber protection gap and the rapid evolution of data privacy regimes across the region.
“We continue to see a significant long-term growth opportunity for cyber insurance across APAC,” Poh added.
“While the market has developed considerably over the past decade, cyber insurance penetration in many APAC markets remains relatively low compared with more mature markets. That creates meaningful runway for sustainable growth.”
The key drivers include continued digital transformation across industries, expanding regulatory, privacy and disclosure obligations, greater board-level awareness of cyber risk, growth in cloud adoption and AI, and rising expectations from customers, investors and business partners around cyber resilience — alongside growing recognition that cyber risk can create material operational, financial and reputational consequences.
To capture these opportunities, Sompo has strengthened its financial lines team over the past year.
“We will continue investing in underwriting expertise across key product lines,” she added.
“These investments reflect our ambition to be one of the leading financial lines insurers in the region and to provide consistent, high-quality support to our clients and broker partners.”
Fresh from adding Malaysia to its Asia footprint, specialist (re)insurance broker Miller will prioritise deepening and broadening its capabilities and “scaling the businesses in territories we are already in”, according to APAC head of treaty reinsurance, Richard Broad.
Miller Malaysia’s initial offering under its Labuan licence will focus on treaty and facultative reinsurance, with plans to broaden its product capabilities, it said in September.
“Our newly launched Miller Malaysia business will allow us to further expand our reinsurance capabilities through fac and treaty business in the region. We are focused on building our relationships with Malaysian cedents and attracting regional talent to an alternative hub,” Broad said.
In May, head of Asia Ron Whyte had said following its successful entry into Japan and South Korea, the broker would continue its selective expansion in Asia, with Malaysia on the cards.
Miller had opened its South Korea operation in 2025 having acquired Japanese broker Lead Insurance Services in 2022.
According to Broad, Miller has grown its Singapore presence over the last five years and has mirrored many of the specialist capabilities it has in London, while in Japan it has a small but rapidly growing non-marine retail business to support its marine business, with ambitions to develop its presence in the reinsurance space.
In South Korea, Miller has built a “robust and successful” specialist (re)insurance business in under two years, with a focus on marine, affinity, cyber and P&C, with plans to scale the business in additional specialty markets and across retail and reinsurance channels, according to Broad.
“The growth of Asia Pacific, combined with reinsurers’ global diversification strategies, is fuelling capacity for the region across most lines of business,” added Broad.
“We are seeing an increased number of MGAs across the region, which adds further competition to the existing players, all looking for growth and expansion.
“This trend will continue and ensures that new reinsurance products can be brought to market to manage complex and evolving risks.”
And while the region has largely been spared major catastrophe losses, the floods in Thailand and earthquakes in Japan have offered reminders of the potential for losses.
“Asia Pacific will always have catastrophe losses and each country has its own unique underlying risk complexity and associated catastrophe pricing,” Broad said.
“When catastrophe losses occur which are considered to be outside the expected modelling, reinsurers will need to allow for this in the renewal pricing.
“Market competition, both from existing reinsurers and new entrants, will certainly reduce the impact of significant price corrections, allowing clients to manage the renewals appropriately.”
Broad expects solid reinsurer results, strong market capital levels and competition for market share to continue and drive the trend towards a buyer-friendly market for the 1.1 renewal season.
“Markets across Asia Pacific vary substantially by territory, class and loss experience, so the individual client results remain very much dependent on the quality of the underlying portfolio and reinsurer relationships,” he said.
“This year, we have seen clients strategically using the competitive market conditions to enhance their reinsurance protections and redeploying any savings on offer to purchase additional programs, layers or alternative multi-year solutions – this represents a positive opportunity for the market.”
Broad has noted an increased supply by reinsurers and increased demand by clients for structured solution products, allowing clients to enhance their overall risk management strategy.
“Most clients are looking at maximising the value from their reinsurance spend without any detrimental impact on the protection they need,” he said.
“With the support of even more robust reinsurance programs, clients will have a platform for greater growth and product innovation moving forwards.”
Broad does expect further softening, but said reinsurers will remain disciplined.
“Reinsurers will remain disciplined on how much softening is achievable for each client and in each market,” Broad said.
“Flexibility on T&Cs to assist with individual clients’ growth strategies in their respective markets will no doubt be a key negotiation and discussion point throughout pre-renewal meetings.”
The steep ongoing softening in Asia Pacific’s reinsurance market masks a proliferation of risk in the region, according to Sri Ram Pappu, deputy CEO of Antares Singapore.
Pappu said that the coming 1.1 renewals will be shaped by four factors, creating a complex multispeed marketplace.
“Capacity is abundant — at the start of this year APAC had over 130% of the capacity it needed, and more has arrived since,” Pappu said. “Pricing follows that: in financial lines, Asian rates have now fallen for more than three years and were down 7% in the second quarter alone. Retentions are the quiet one; buyers are keeping them broadly where they are and putting the savings into more limit.”
Due to the sustained market softening, and intense competition due to the abundance of capacity, reinsurers now face intense pressure to loosen terms and conditions, with wordings being “where the real negotiation will be”, Pappu said.
“In cyber, cover is being stretched to pick up AI, fraud and physical damage,” he added. “Rate is a cyclical conversation while coverage is a structural one. Insurers need to be far more careful when adapting to structural change, and it is important that we communicate this to clients.”
Most lines of business in APAC have seen double-digit rate reductions over the past 12 months, with financial lines and property catastrophe being particularly soft.
The steep softening masks an environment where risk is intensifying, which is not being reflected in the current rates across multiple lines of business.
“Risk is moving faster than price,” Pappu said. “Ransomware hit a record in the first half of this year, including a record half for Asia and Oceania, yet cyber rates have fallen for four years running. Hull and machinery went into 2026 only marginally profitable, with ageing fleets and higher repair costs. And in D&O, regulators in Hong Kong, China and Southeast Asia are all stepping up enforcement just as cover has become cheaper.
“None of that shows up in a single renewal. It shows up two or three years later, in the claims. That gap — between where the risk is heading and where the price is heading — is the conversation we as underwriters have every week.”
At the coming 1.1 renewals, the carrier will seek to grow in marine and financial lines, particularly cyber, which it sees as its core strengths, while limiting its exposure to proportional treaties that do not meet its pricing expectations.
“Our appetite is growing, but deliberately,” Pappu said. “We want to do more in the classes where we have real depth — marine and financial lines — and in cyber, where we’re still scaling our proposition. We won’t follow the market into business that’s priced below the risk.”
According to Pappu, the primary softening of proportional treaties is a “major concern,” while on quota shares, which inherit original rates, cedents have pushed for higher commissions.
“Falling rates and rising commissions squeeze the margin from both ends,” Pappu added. “Our approach is straightforward: we wl back cedents whose original pricing is holding up, and we will be transparent where it isn’t.”
Antares sees long-term opportunities in marine cargo in Asia, which accounts for 30% of the world’s marine premium and is a major driver of global cargo growth.
“Asia now writes close to 30% of the world’s marine premium and leads global cargo growth, much of it out of China, which we write from Singapore,” Pappu said.
“That’s where our marine franchise needs to be strongest,” he added.
Despite the current softening, financial lines is also a strategic priority for Antares, with booming equity capital markets across APAC, particularly Hong Kong, creating long-term demand for D&O coverage.
“Equally important is that we won’t chase classes where capacity has run well ahead of the risk,” Pappu added. “Choosing where not to grow is as much a strategy as choosing where to grow.”
Taiping Re is studying selective expansion of its pioneering ILS program in Hong Kong following the recent moves to introduce sidecars and protected cell companies (PCC) in the territory, according to the Chinese reinsurer’s CEO.
Sheldon Yu said that the reinsurer was actively monitoring the market following the establishment of its catastrophe bond program since 2024 and its recent backing of the first-ever Hong Kong-domiciled sidecar.
“Since Taiping Re established a dual-pillar risk diversification framework combining traditional reinsurance with insurance risk securitisation in 2024, the company has been keeping pace with the ILS market space,” said Yu. “Looking ahead, the company will remain active in ILS market and explore various products to fuel business growth.”
Taiping Re has been heavily involved in the development of Hong Kong’s local ILS market since the establishment of the pilot grant scheme by the Hong Kong government in the 2021-22 budget.
In January 2025, Taiping Re became the sixth company to issue ILS in Hong Kong when it raised US$35 million from the sale of a catastrophe bond via Silk Road Re, its Hong Kong-domiciled special purpose vehicle (SPV). The bond was also the first to be tied to multiple perils and triggers.
In October, Taiping Re was also one of the principal investors in PICC P&C’s HK$94 million (US$12 million) sidecar, the first-ever locally domiciled third-party capital reinsurance vehicle in Hong Kong.
According to Yu, the nascent market is primed for further rapid growth following the Hong Kong government’s recent move to introduce a regulatory regime for PCCs, which make structuring ILS and captives cheaper and easier for insurers as it enables the creation of multiple ring-fenced cells within the same legal entity.
“In the SAR government’s first five-year plan for economic and social development, Hong Kong is strategically positioned as an international risk management centre,” Yu said. “The PCC regime plays a vital role in ILS and captive operation. PCC is a specialised corporate structure enabling the ringfencing of assets and liabilities within a single legal entity utilising multiple cells.
“It reduces transaction cost of launching a new [SPV] for every individual deal and ensures ILS investors in a cat bond or sidecar contract being only exposed to their chosen risk.”
The arrival of the new PCC regime is a “revolutionary breakthrough”, which will enhance Hong Kong’s international competitiveness in attracting captives and ILS issuance, Yu added.
At the coming 1.1 renewals, Taiping Re expects a continuation of the global reinsurance market softening, with an abundance of capital outpacing demand across Asia Pacific following another year of benign insured natural catastrophe losses in the region.
“Driven by strong reinsurance capital, satisfactory underwriting margin, and an absence of market-turning catastrophic losses, overall market pricing is expected to remain under downward pressure, tracking rate reductions in the direct market,” Yu said.
“Cedents are positioned to capitalise on favourable market dynamics to secure higher limits, broader coverage or attritional protection without significantly increasing overall cost.”
Despite overall insured natural catastrophe losses remaining benign in 2026, APAC faces more frequent extreme weather patterns due to the arrival of El Nino, which triggers extreme heat, major rainfall, severe drought and destructive typhoons.
During the Northwest Pacific typhoon season so far, there have been over 30 named storms and 13 typhoons, including 10 very strong typhoons and four violent typhoons, including Typhoon Champi in October, which was the most powerful storm globally this year.
The volatile weather patterns will influence how cedents structure their property catastrophe programs at the forthcoming renewals.
“The pricing of natural catastrophe reinsurance programs shall have the trend taken into consideration,” Yu added. “Renewal prices will remain highly risk differentiated. Accounts or specific layers severely impacted by recent events will have appropriate rate adjustments to reflect the loss.
“At the same time, we expect that cedents would take advantage of the market condition to seek wider protection without substantially raising budget.”
The coming 1.1 renewals in Asia Pacific are expected to be challenging for reinsurers as the market softening continues amid intense competition for business, according to Pavlos Spyropoulos, managing director of APAC at Tokio Marine Kiln in Singapore.
Spyropoulos said that the (re)insurance market in the region has entered “a challenging phase in the cycle.”
“When you speak to both our underwriters, but also when we’re speaking to brokers, we’re seeing all the pressure come in in terms of competition and the impact that’s having on the rating environment,” he said.
Another year of benign natural catastrophe losses and strong reinsurer earnings has created a complex market where capacity is abundant, rates are softening but risk is proliferating.
“Risk is heightened everywhere you look including in the region as well, and at the same time there is an oversupply of capital and capacity which is having an impact on rates,” Spyropoulos added.
The industry currently faces acute risks from the conflict in the Middle East, which has had a huge impact across the specialty market this year, particularly in the marine market, and from the ongoing AI and data centre boom that is in full swing in Asia Pacific and around the world.
“We are now seeing interest rates going back up in some key economies,” Spyropoulos added. “You’re seeing quite significant loss activity in certain lines of business and heightened risk. We know obviously the Middle East conflict is driving a lot of that in areas like political violence and terrorism.
“There’s some emerging risk as well. On the marine cargo side, the values of shipments of high-tech components have gone up significantly. We keep having the boom in AI, and we’re seeing quite significant loss activity with theft of this cargo. And yet we’re in a period where the cargo market is still seeing continued rate reductions in recent months.”
According to Spyropoulos, rate adequacy is becoming a major concern for the market given this complex risk landscape, although there are specialty lines such as political violence and terrorism (PVT) that are starting to see a reversal of the softening trend.
“I think there’s probably a reckoning coming in certain lines of business,” Spyropoulos said. “I think in the primary and facultative markets, it’s certainly a hot theme. It’ll be interesting to see how the reinsurers are going to be responding to it as well.”
For the PVT market, 2026 has been a “whirlwind” year with the crisis in the Middle East and heightened prospects of civil unrest across APAC due to higher energy prices driving significant “recalibrating” of appetite among buyers, according to Spyropoulos.
“I think that’s going to continue throughout the year, particularly as people go through their treaty renewals,” Spyropoulos said. “I think capacity might become more constrained. That’s certainly what I would expect.
“I’d expect that to be quite a dynamic marketplace over the next six to 12 months.”
TMK currently sees significant opportunities in the specialty market in APAC heading into 2027, particularly in Southeast Asia, where the specialty insurer recently expanded its footprint in the marine market through its backing for marine MGA Rokstone Underwriting’s launch in Singapore.
“I think despite the challenging market conditions, we’re still finding ways to grow and, to touch wood, it should be another year of profitable growth for our business,” Spyropoulos said.
“What we’re focusing on is I’d say diversification in multiple ways, one being geographic. We want to make sure that we’ve got broad distribution across the region and making sure we’re tapping into markets where perhaps we’ve not had as significant growth as we have in the past.
“I think particularly Southeast Asia is an area we’re looking at because we’re very strong in the Pacific region and North Asia and we see opportunities to do more in Southeast Asia.”
Vietnamese reinsurer Hanoi Re is prioritising a broadening, but selective, risk appetite amid the current soft market, CEO Trinh Anh Tuan said.
“We intend to support our clients through this cycle and can be flexible in the share we take and the structures we support. That flexibility has technical limits,” Trinh said.
“We are prepared to compete for business, but not at any price, and where terms no longer support a sound underwriting decision, we will step back.”
While open to new markets, the reinsurer prioritises well-managed clients with familiar risks and underwriting.
“We are open to insurance needs arising from technology, AI and electric vehicles, and we are interested in parametric solutions,” he added.
“In each case, our participation depends on how clearly we can see the exposure, the coverage and how the risk will be managed.”
Rate adequacy is a real concern, and proportional treaties are where it bites first, according to Trinh.
“A cut in the cedent’s rate is a cut in ours, often accompanied by a request for higher commission. So we look beyond the treaty terms to the original rates, deductibles, coverage, loss trends and accumulations underneath them,” he said.
He expects the softening seen at this year’s Asian renewals to continue into 2027, giving cedents in Vietnam, as elsewhere in the region, more choices.
He also observed that wordings have broadly held up better than pricing so far this year, which is healthy.
“Concessions on wordings are harder to see than concessions on price, and they tend to surface only when a loss arrives. Where we participate, we read the wording as closely as the price,” Trinh said.
Rapid economic growth magnifies nat cat risks in Vietnam, highlighted by Typhoon Yagi in 2024, which caused extensive damage across major industrial areas in northern provinces.
“One storm does not make a trend, but as more valuable assets are concentrated in the same industrial parks, ports and logistics corridors, the same event produces a much larger loss,” he said.
Much of that loss is not physical, Trinh said, as business interruption and supply-chain dependencies can extend a claim well beyond the damaged site, making exposure accumulation as critical to assess as single risks.
Data centres and battery energy storage systems add a different kind of complexity due to concentration of high-value equipment, he said.
“My main concern is that competition is moving faster than risk understanding. In Vietnam, asset values have risen quickly with industrial growth, but sums insured and exposure data do not always keep pace.”
Trinh Anh Tuan, Hanoi Re
Meanwhile, AI presents a dual threat, empowering insurer pricing and cyber attackers, he added.
“My main concern is that competition is moving faster than risk understanding. In Vietnam, asset values have risen quickly with industrial growth, but sums insured and exposure data do not always keep pace,” Trinh said.
“Combined with falling rates, that can leave the market underpricing exactly the accumulations that Yagi exposed. Across Asia, the same pressure can push decisions towards short-term premium growth or cost savings.”
He advised cedents to leverage the current market conditions to enhance exposure data, update asset values, and refine risk retention.
Cedents should also focus on partners with not only financial strength and credit ratings but also a track record of honouring their commitments.
“The real test of a reinsurance relationship comes when a claim is made, not when a renewal is signed,” Trinh said.
Vietnam and Southeast Asia will remain the core of Hanoi Re’s business over the next 12 months, with China and South Korea continuing as important drivers of growth beyond the home region, the CEO said.
“Vietnam is where our market knowledge is deepest, and industrial, infrastructure and energy investment continues to create demand for reinsurance capacity and technical support,” he said.
“In China and Korea, we have worked with cedents and brokers for many years; our priority now is to deepen and broaden that cooperation where our knowledge of the business supports it.”
Treaty reinsurance is Hanoi Re’s clear priority, while in facultative, it focuses on engineering and property, where it has deep expertise.
“Agriculture is an area we are particularly keen to develop further. It matters greatly to Vietnam’s economy, and well-designed reinsurance can help that market grow,” Trinh added.
A pronounced softening cycle is driving increased demand for facultative reinsurance in a riskier Asia-Pacific market, according Rob Drysdale, senior partner at cedent facultative specialist broker Consilium.
“On the supply side, reinsurance capacity is plentiful giving cedents more options, and on the demand side, premium reductions are increasing motivation for cedents to transfer more volatility from their portfolios,” he said.
The rate movements, according to Singapore-based Drysdale, have been striking.
“Rate reductions have been particularly large this year in the facultative market and it hasn’t been uncommon to see rate reductions above 40% for some lines of business in certain territories,” Drysdale added. “We even had one client joke recently that ‘last year’s brokerage is this year’s premium’.
“A soft market and abundant capacity give clients greater choice, but demand reinsurer discipline.”
That pricing environment is fuelling a specific kind of appetite.
“There is strong demand from cedents to remove volatility and attrition losses, and we have seen considerable interest in spot fac purchases,” Drysdale added.
Yet the soft market tells only half the story, as even with abundant capacity, the underlying risk landscape is growing more complex and that is sharpening the case for buying protection.
“The backdrop is also riskier,” Drysdale said. “New and emerging exposures such as cyber and AI, the effects of climate change, and rising geopolitical tensions, all weigh on the picture and increase the attractiveness of buying reinsurance. From a regional perspective, Asia is also more exposed to these risks than others.”
Fac is particularly well suited to this environment, he added, because it allows clients to target protection with precision.
“Examples include purchases for specific locations on global programs which are more exposed to nat cat or involved in a higher risk occupancy than the rest of the schedule,” he said.
“This is where facultative reinsurance is an effective tool as it enables clients to make very bespoke purchases.”
Drysdale was careful to stress that the softening is far from universal.
“Not every line of business and territory is softening universally,” he said.
“Rates in some countries are holding up better than others, and there are even pockets where the market has hardened, such as marine war and political violence in the Middle East, where rates are obviously much higher than they were before the conflict in the Middle East. ”
That divergence, he added, is precisely why cedents continue to value fac.
“This shows how quickly the picture can change, and why cedents value protection in the areas where they may feel more vulnerable,” he said.
Regulation is another force shaping how facultative business is placed with India a case in point.
“India is a good example as recent regulations there have put significant restrictions on offshore reinsurance, and with the emergence of Gift City, has added local capacity and contributed to considerable pricing pressure,” Drysdale said.
With its Singapore office less than a year old, Consilium sees opportunity across the region, particularly given the wave of infrastructure investment underway.
“For us, growth opportunities are everywhere, especially with the investment in infrastructure projects across the region,” Drysdale said.
The firm intends to build on its early momentum.
“We’re building on a strong start and will keep investing in both talent and capability in the region,” he said.
“Alongside our core lines of business, we’re seeing more opportunities than we initially expected in casualty, marine and financial lines, and we expect to continue broadening our offering as client demand develops.”
But expansion will not come at the expense of discipline.
“We’ll expand in a measured way, adding capability where we can deliver real value for clients rather than chasing volume,” he said.
“Our aim is simple: to be the independent wholesale and facultative reinsurance broker of choice for clients in Asia Pacific.”
Satellite data specialist ICEYE envisages further possibilities for its catastrophe intelligence as it expands its footprint across Asia Pacific, suggesting that it can now be used to assist insurers with underwriting and pricing.
The company, which has built its insurance proposition around rapid observation of natural catastrophes, increasingly sees the historical data generated from hundreds of past events as a tool for understanding risk before a loss occurs, rather than simply responding post-event.
Australia is currently ICEYE’s largest market in Asia Pacific in terms of the breadth of insurance adoption, with Japan another major market after it began its insurance penetration of the market in tandem with Tokio Marine in 2020. More recently, it has announced that Sompo Japan is now using its flood insights data.
The company is currently broadening its reach across Asia, adding flood coverage in India, Thailand, Vietnam, the Philippines, Taiwan and South Korea.
India in particular represents an important growth market after ICEYE opened an office and is investing in its local operations as it seeks to expand insurance and public-sector use of its catastrophe intelligence.
“The biggest growth areas in terms of use of the technology will be flooding in the Asian countries that we’ve added, and tropical cyclones, assuming that there continues to be large events.”
Stephen Lathrope, ICEYE
For the time being, flood and tropical cyclone-related solutions are likely to provide the biggest opportunities for further adoption across Asia Pacific, given the region’s exposure to both perils, according to Stephen Lathrope, senior vice president for solutions.
“The biggest growth areas in terms of use of the technology will be flooding in the Asian countries that we’ve added, and tropical cyclones, assuming that there continues to be large events,” he said.
ICEYE uses its synthetic aperture radar satellites to observe catastrophe events regardless of cloud cover or darkness, allowing it to map the extent and depth of flooding and assess damage to buildings following major events.
The technology has traditionally been used to help insurers understand losses quickly, deploy adjusters and other resources, and accelerate claims payments, however, ICEYE increasingly sees the archive generated from previous events as valuable in its own right.
After around five years of flood observation, the company has assembled data from around 600 floods across more than 35 countries, and rather than modelling where water theoretically might go, the archive provides observations of where it actually went during past events, including flood extent and depth.
Lathrope said Australian insurer QBE has used the data to improve its understanding of issues, including differences in restoration costs following flooding.
He suggested, the development reflects a broader shift in the use of Earth observation data from principally managing catastrophe response towards informing risk selection and pricing.
In August, ICEYE announced a partnership with Louisiana-based The Water Institute to bring its FloodID predictive intelligence platform and core development team into ICEYE.
The aim is eventually to combine forecasts of where water is likely to go with ICEYE’s satellite observations of where it actually goes during an event.
“We’re not trying to become a cat modelling company,” Lathrope said. “What we are trying to do is be the absolute best at supporting clients’ preparation and response to nat cat events.”
Parametric insurance represents another significant opportunity for satellite observation in Asia, he added, particularly in markets where conventional insurance penetration remains low.
ICEYE already supplies data for parametric arrangements designed to address protection gaps in Africa, and Lathrope said he believes similar structures could be deployed across Asia.
In June, Liberty Mutual Reinsurance and ICEYE launched a building-level parametric wildfire product for Australia and the US. The system uses satellite imagery, property footprint data and machine learning to determine whether individual buildings have been destroyed, potentially allowing pay-outs to be triggered within days.
“I think it’s got huge potential,” Lathrope said. “There is absolutely no reason why this couldn’t be applied in Asia.”
HDI Global is maintaining a long-term approach to underwriting Asian risk rather than reacting to individual market cycles, Alex Tarantino, managing director and principal officer at HDI Global SE Singapore, said.
The insurer is placing underwriting discipline at the centre of its Asian growth strategy, warning that capital is no longer the binding constraint.
“Asia continues to offer some of the most attractive growth opportunities globally, but success will depend on maintaining underwriting discipline, embracing innovation and building long-term partnerships that can navigate an increasingly complex risk landscape,” Tarantino said.
Tarantino also outlined HDI Global’s priorities for the year ahead.
“One key theme we’re seeing for upcoming renewals is that, if capital is no longer the constraint, underwriting discipline is,” he said.” Reinsurers are increasingly selective and rewarding underwriting quality, data transparency and sustainable primary market pricing.
“Looking ahead to the upcoming renewal, we continue to emphasise disciplined underwriting, supported by specialist expertise and strong risk engineering capabilities.”
The region is also becoming more complex, Tarantino added.
“Asia continues to be one of the most dynamic and attractive growth regions globally, but it is also becoming increasingly complex from a risk perspective,” he said.
“Natural catastrophe exposures remain a significant concern, particularly given the frequency and severity of secondary perils and evolving climate patterns. At the same time, geopolitical risks, supply chain disruption, energy transition challenges, cyber threats and increasing asset values are creating new concentrations of risk.”
“We are also seeing substantial investment across infrastructure, renewable energy, high technology manufacturing, digital assets and energy security projects throughout Asia.
“These sectors offer considerable opportunity but require increasingly specialised underwriting expertise and risk engineering capabilities.”
HDI’s appetite for Asia remains strong, with the region central to HDI Global’s long-term growth ambitions, according to Tarantino.
“We continue to see attractive opportunities across both mature and developing markets, and across energy, infrastructure, manufacturing, technology and multinational programmes,” he added.
“We are also seeing signs of increased competition in some primary market segments.”
He added that rate adequacy may become a concern for primary insurers and reinsurers.
“In energy, property and marine, we continue to support high-quality risks where underwriting information, pricing, risk management standards and portfolio performance justify our participation,” Tarantino said.
“That said, growth must be profitable and sustainable so that we can act reliably in the long term. We remain cautious where pricing does not adequately reflect underlying exposures or loss cost trends.
Tarantino said that HDI’s strategy is centred on profitable growth, strengthening partnerships and expanding its relevance to clients across Asia.
“Southeast Asia remains a key focus. Markets such as Indonesia, Thailand and Malaysia offer significant long-term potential, supported by economic growth, industrialisation, infrastructure investment and increasing demand for sophisticated risk transfer solutions,” he said.
From a business-line perspective, HDI sees opportunities across energy, including conventional power, renewables and upstream.
Marine, property and engineering, financial lines and cyber, multinational solutions, alternative risk transfer, and captive solutions also present opportunities, with HDI eyeing opportunities to bring more of its specialty capabilities across Asia.
“Urbanisation, infrastructure development, interconnected supply chains and emerging technologies can all create accumulations that are not always immediately visible. As a result, risk profiles are evolving faster than ever.”
Alex Tarantino, HDI Global
The key challenge, Tarantino said, is managing growing exposure concentrations and keeping pace with rapidly changing risks in an increasingly competitive market.
“Urbanisation, infrastructure development, interconnected supply chains and emerging technologies can all create accumulations that are not always immediately visible. As a result, risk profiles are evolving faster than ever.”
He also advised cedents on the importance of high-quality data and relationships.
“For cedents, high-quality data, strong portfolio analytics and early, transparent dialogue with risk carriers become increasingly important.
Long-term relationships help all parties develop a shared understanding of exposures and manage volatility sustainably.”
“The strongest relationships are built over multiple market cycles, where both sides share information, understand exposures and work together to manage volatility, rather than focusing only on the conditions of the next renewal.”